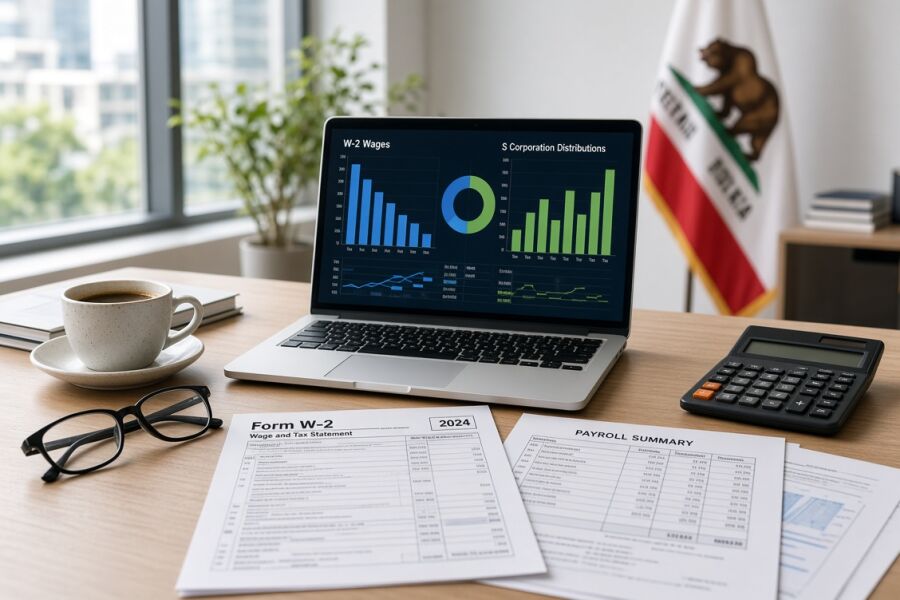
Reasonable Compensation for S Corp Owners: California’s Algorithms are Flagging Low Salaries
S corporation owners who work in the business have long been required to pay themselves reasonable compensation as W-2 wages for services performed before taking distributions. The IRS has emphasized this for years (see IRS Fact Sheet FS-2008-25, August 2008). What has changed is the speed and scale of enforcement—especially in California.
California’s Franchise Tax Board (FTB) and Employment Development Department (EDD) are now using algorithmic and AI-driven matching to cross-check W-2 wages against S corporation distributions and other records. Seemingly minor anomalies, such as reusing the exact same salary figure year after year without updated support, can trigger reviews or adjustments without a human examiner necessarily reviewing the return first. Tax professionals have noted that “as goes California, goes the rest of the country,” with the IRS expected to expand similar data-matching tools.
The Core Rule Has Not Changed
Under longstanding federal law and IRS guidance, an S corporation officer who performs more than minor services is an employee. Payments for those services must be treated as wages subject to employment taxes, not as distributions, loans, or other non-wage payments. The amount of compensation cannot exceed what the shareholder receives (directly or indirectly), but if the shareholder receives anything, a reasonable salary must be determined and paid.
There is no fixed percentage, “60/40 rule,” or statutory safe harbor. Courts and the IRS look to facts and circumstances. The factors highlighted in FS-2008-25 remain relevant:
- Training and experience
- Duties and responsibilities
- Time and effort devoted to the business
- Dividend/distribution history
- Payments to non-shareholder employees
- Timing and manner of paying bonuses
- What comparable businesses pay for similar services
- Compensation agreements
- Use of a formula to determine compensation
Comparable market data (what a non-owner would be paid for the same work under similar circumstances) is typically the strongest and most heavily weighted factor. Approaches used in analyses often include market data, a “many-hats” cost approach that prices the different roles the owner fills, and an independent-investor perspective on residual profits.
Why California Raises the Stakes
California adds several layers that affect both the economics and the audit risk:
- S corporations pay a 1.5% entity-level franchise tax on net income (with an $800 minimum). Salary is deductible, so it reduces the base for that tax, but distributions do not.
- California SDI is uncapped. Higher wages therefore carry ongoing state disability cost on every dollar, unlike the federal Social Security wage base.
- EDD independently scrutinizes payroll compliance and can pursue its own assessments. An IRS reclassification of distributions as wages frequently creates corresponding California payroll reporting and withholding issues (DE 9 / DE 9C and related filings).
- California does not conform to the federal Qualified Business Income (Section 199A) deduction. Salary-optimization calculations that look attractive on a federal return do not produce the same state benefit.
In short, a salary that is defensible federally still needs to be reviewed in the California context, and static or poorly documented numbers are more likely to be flagged by automated matching.
Practical Steps That Hold Up
The strongest defense is an annual, documented analysis tied to the actual services performed that year. Key practices include:
- Benchmark against current, independent data (BLS occupational data for the relevant metro area, industry surveys, job postings, and what you pay non-owner employees for comparable work).
- Document the owner’s role, hours, duties, and any changes from the prior year.
- Avoid simply copying last year’s salary or applying a fixed percentage of profit or revenue without supporting analysis.
- Keep contemporaneous records (job description or role summary, time estimates, market data sources, and a short memo explaining the conclusion).
- Run real payroll, withhold and remit federal and California taxes, and issue a proper W-2. Distributions are reported separately on Schedule K-1.
Zero or near-zero salary alongside material distributions remains the clearest red flag. Conversely, overpaying salary increases payroll tax cost without additional tax benefit once reasonable compensation is reached.
If the business is unprofitable and the owner takes nothing out, there is generally no requirement to create a wage. Once distributions (or other benefits) are taken for services performed, the reasonable-compensation requirement applies.
Why This Matters Beyond Compliance
Reasonable compensation is not only an audit-defense issue. It affects cash flow, the cost of the S election versus other structures, Social Security earnings records, and the overall tax picture for the owner. In a high-tax state like California, the interaction between federal employment taxes, the 1.5% franchise tax, uncapped SDI, and the lack of a state QBI deduction means the “right” number is rarely the absolute lowest number that might have been defensible a decade ago.
Annual review—supported by market data and a clear explanation of the services performed—puts owners in the strongest position when algorithms (or examiners) compare wages to distributions. It also supports better decision-making about entity structure, compensation design, and cash extraction.
If you own or operate an S corporation in California (or are evaluating one), the combination of longstanding federal rules and newer automated state matching makes proactive, documented analysis more important than ever. A facts-based figure prepared before the return is filed is far easier to defend than an after-the-fact explanation.
(This is Blog Post #1976)
Related Posts
About the Author: Roger Rossmeisl, CPA